UK consults on default pensions: what guided retirement would change
The November 3 consultation concerns income from workplace pension pots. Proposed compliance dates begin in summer 2029, with later deadlines for some schemes.
Verified brief
The story in 60 seconds
The government has opened a consultation on how defined contribution workplace schemes should offer default retirement-income options. Members would retain choice. The implementation timetable is indicative, and the plans do not announce an immediate increase in State Pension payments.
This brief and the full story below are based on the disclosed sources. SearchTrends Daily’s interpretation appears later under “Our take.”
Full reporting
The complete story
The Department for Work and Pensions announced two consultations on November 3, 2026: guided retirement and draft rules for Retirement Collective Pension Schemes. The first asks how providers should offer default options for turning workplace pension savings into retirement income.
The guided retirement exercise runs until December 22, 2026. It was developed with HM Treasury, the Financial Conduct Authority and The Pensions Regulator. Its proposals address both trust-based and contract-based workplace arrangements.
The detailed paper projects summer 2029 compliance for most master trusts and FCA-regulated schemes. It projects summer 2030 for common-employer group master trusts and single-employer trusts. Master trusts planning a Retirement Collective Pension default would have a summer 2029 strategy deadline and summer 2030 deadline for the default itself. These are indicative dates, subject to feedback and Parliamentary agreement.
Source perspectives
What other reporting adds
These are the reports, official records, and trend observations used to build the story. The note under each link explains exactly what it contributes.
Primary announcement of two consultations, the income objective and the continuing ability to choose another option.
Read original source ↗DWP / FCA / The Pensions RegulatorGuided retirement policy consultation — November 3, 2026Primary policy proposals, December 22 closing date and Chapter 7’s indicative compliance timetable and conditions.
Read original source ↗The Pensions RegulatorPension Schemes Act 2026 — default pension plan requirementsExplains the Act’s framework, the role of secondary legislation and trustees’ design, communication and partnership responsibilities.
Read original source ↗Financial Planning TodayGovernment announces consultation on ‘guided retirement’ — November 3, 2026Independent specialist reporting confirms the consultations and attributes a concern about preserving pension choice to LCP partner Steve Webb.
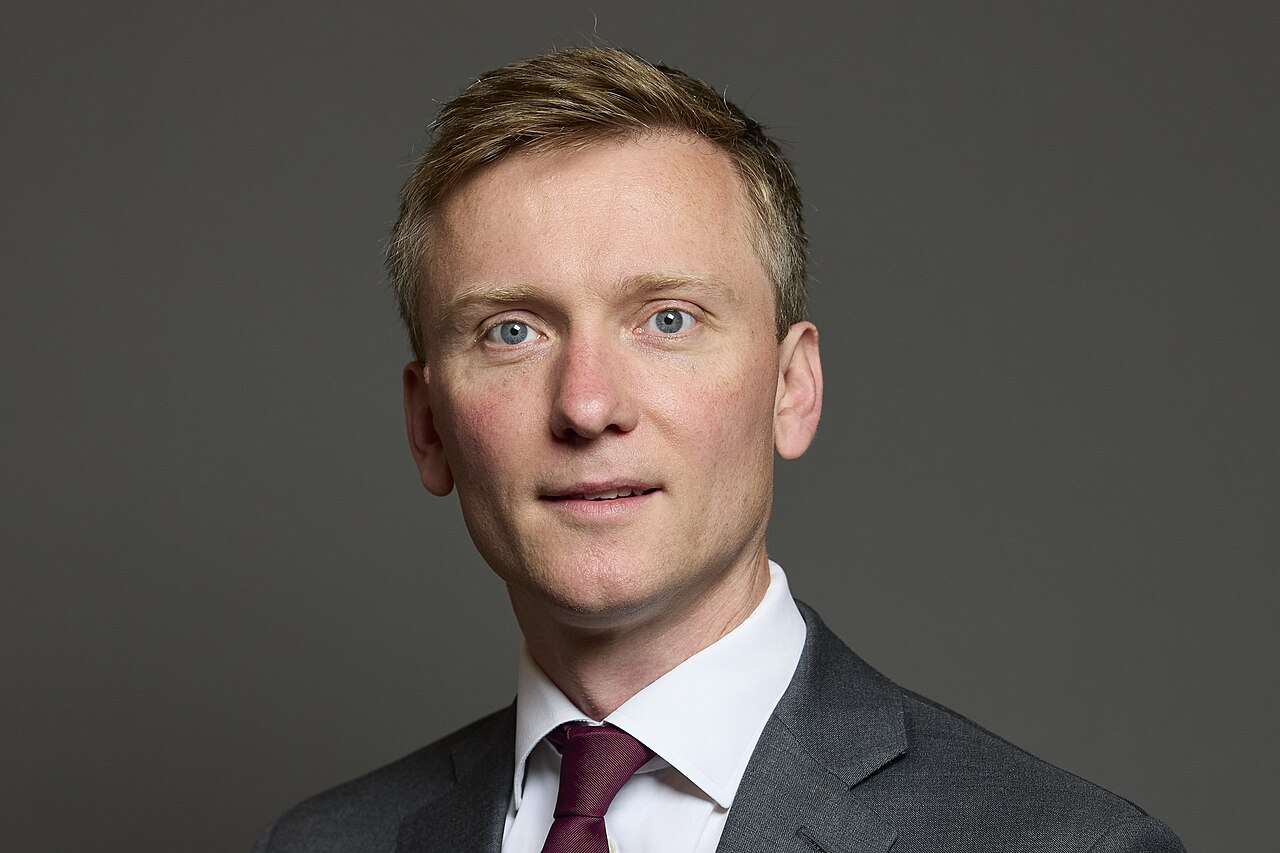
Read original source ↗Wikimedia Commons / House of Commons / Roger HarrisOfficial portrait of Torsten Bell MP — 3:2 cropOfficial portrait photographed July 15, 2024, credited to House of Commons / Roger Harris. Archival image, not an announcement photograph.
Read original source ↗Creative CommonsCreative Commons Attribution 3.0 licenceLicence for the credited portrait. Existing source crop retained; website display may crop it further.
Read original source ↗SearchTrends Daily opinion
Our take
Analysis
What the evidence and search signal suggest
Our assessment: the key test is how providers balance a usable default with meaningful member choice. A timetable extending into 2029 and 2030 also means today’s announcement should not be presented as a new payment starting immediately.
Analysis and commentary are SearchTrends Daily’s interpretation. They are intentionally separated from the sourced account above.
Meaning
Why this matters
The policy focuses on the step from building a defined contribution pot to drawing an income. DWP says schemes would take more responsibility for offering a route intended to last through retirement, while savers would remain free to choose another option.
A default option is not a promise that everyone will receive the same payment. The proposals concern workplace savings and provider responsibilities; they do not announce a rise in the State Pension.
Background
How we got here
The Pensions Regulator says the Pension Schemes Act 2026 establishes new requirements for most defined contribution schemes, with secondary legislation to specify the exact requirements and scope. Its guidance describes trustees designing one or more defaults around their members’ needs, communicating them and potentially partnering with other providers.
Today’s consultation addresses implementation rather than declaring the whole system operational. Financial Planning Today independently reports the two consultations and records LCP partner Steve Webb’s concern that an emphasis on lifetime-income products could constrain practical choice.
Outlook
What is likely to happen next
The next steps are consultation responses, final regulations and FCA rules. The current paper explicitly leaves its projected timetable subject to change. This explainer reports the policy process; it does not recommend transferring a pension, buying an annuity or changing withdrawals.
Image credit: © House of Commons / Roger Harris, CC BY 3.0, via Wikimedia Commons. This is Torsten Bell’s official parliamentary portrait, photographed July 15, 2024, in the source’s existing 3:2 crop. It is an archival portrait, not a photograph of the November 2026 announcement. The site may crop its display.
A conditional editorial assessment based on the evidence available at the review date, not a guaranteed outcome.
Live record
Updates to this story
No material updates yet.
Commentary
What we think
Clear reporting should distinguish the government’s policy aims from final scheme terms. Those terms, including how risks and flexibility are handled, will matter more to an individual than a slogan about a pension for life.